The product diversification of financial institutions and insurance companies, resulting in overlapping of products and services strengthens the case for the merger of the two regulatory agencies, namely SEBI and IRDA. Justify. (UPSC 2013)
Product diversification has blurred the line between capital market instruments and insurance products. When one product offers investment, protection and savings together, separate regulators can create overlap, confusion and gaps in supervision.
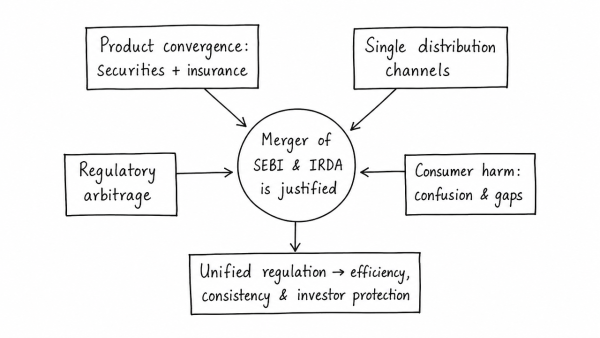
- Product convergence: ULIPs, market-linked pension plans and variable annuities combine features of securities and insurance.
- Single distribution channels: Banks, fintech platforms and financial conglomerates sell both mutual funds and insurance, making entity-based regulation less effective.
- Regulatory arbitrage: Firms may package an investment product as insurance to escape stricter SEBI norms on costs and disclosure.
- Consumer harm: Different grievance systems and mis-selling rules weaken investor protection and increase uncertainty.
- Past conflict: The ULIP dispute showed how turf wars between SEBI and IRDAI can delay policy clarity.
A merger could ensure unified norms, lower compliance costs and give one window for consumers and firms. It would also reduce gaps in systemic oversight, as suggested by reform bodies. However, the complexity of both markets means a merger must preserve specialised skills and strong product-wise supervision.
Originally written on
August 28, 2026
and last modified on
September 7, 2026.