Comment on the important changes introduced in respect of the Long-term Capital Gains Tax (LTCG) and Dividend Distribution Tax (DDT) in the Union Budget for 2018-2019. (UPSC 2018)
The Union Budget 2018-19 changed the tax treatment of equity gains and dividends to widen the tax base and reduce concessionality.
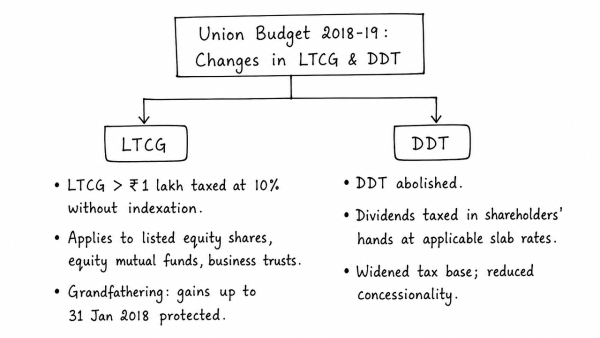
LTCG: Long-term capital gains exceeding ₹1 lakh a year from listed equity shares, equity mutual funds and business trusts were taxed at 10% without indexation benefit. A grandfathering clause protected gains accrued up to 31 January 2018; for assets bought before 1 February 2018, cost was taken as the higher of actual cost or lower of fair market value on 31 January 2018 and sale price.
DDT: A 10% dividend distribution tax was imposed on equity-oriented mutual funds to curb tax arbitrage between dividend and growth options, and higher DDT also applied to deemed dividends.
Overall, these measures made equity taxation less concessional and improved revenue buoyancy.